“Thank you.”
Then I asked him to confirm that no credit inquiry or borrowing commitment would be made in my name without my explicit consent.
He agreed.
When the call ended, I stood beside my truck for several minutes.
Then I opened the photographs I’d taken of the trust.
November twelfth.
Two days after Mom and Nick had begun discussing a mortgage that relied on my income.
I stared at the dates.
The plan was clearer now.
First, tell the bank I would help secure the new loan.
Then sign the trust giving the property to Nick.
Then wait until the balloon came due and present me with a signature line.
I don’t know whether Mom considered it dishonest.
Perhaps she’d convinced herself that family arrangements didn’t need to be explained to everyone affected by them.
Perhaps she believed I would agree because I’d always agreed before.
But I knew one thing.
My name had been used in a financing discussion before anyone asked whether I wanted to be involved.
And two days later, they’d made a written decision excluding me from the property I was supposed to help preserve.
I printed the relevant documents.
Placed them in my own folder.
Then looked toward the calendar.
Thursday.
Two o’clock.
I decided to attend the meeting.
Not to sign.
To make sure everyone understood exactly what they were asking.
Thursday arrived cold and gray.
I left the job site early.
Changed into a clean shirt.
Then drove to Delta Ridge Bank.
As always, I backed my truck into the parking space.
Facing out.
I sat for a moment with my hands on the steering wheel.
Then looked toward the bank entrance.
Pawpaw’s words returned.
You never know when you’ll have to leave.
I took my folder.
Went inside.
And found my family already waiting in Mr. Haskins’s office.
Mom wore her church dress.
Dad had on a freshly pressed blue shirt.
Nick wore a windbreaker with a car dealership’s name embroidered across the chest.
The mounted bass still hung on the wall.
Mr. Haskins stood when I entered.
“Joel. Good to see you again.”
I shook his hand.
“Thank you.”
Mom smiled with obvious relief.
“There he is.”
Then she looked toward Dad.
“I told you he’d come.”
I sat down.
Placed my folder on my lap.
Mr. Haskins arranged his papers.
“All right. If everyone’s ready, we’ll begin with Joel’s credit authorization and review the proposed loan terms.”
I raised one hand.
“Before we start, could I ask two questions?”
The banker looked toward me.
“Of course.”
I opened my folder.
Removed page five of the trust.
Then placed it on his desk.
For a moment, Mom became very still.
I looked toward Dad.
Then read the sentence aloud.
“We have intentionally made no provision for our son, Joel.”
The room became silent.
Somewhere outside the office, a printer started running.
I looked toward Mr. Haskins.
“Question one. Under this trust, who receives the house, land, and workshop when my parents are gone?”
He studied the page.
Then answered.
“Assuming the trust remains effective and the relevant provisions aren’t changed, those assets are designated for Nicholas.”
I nodded.
“Thank you.”
Then I asked the second question.
“If I co-sign this mortgage, and the payments aren’t made, who can the lender require to pay?”
Mr. Haskins folded his hands.
“As a co-borrower, you would be personally responsible under the loan terms. The lender could pursue you for the debt as provided by the agreement.”
I looked toward him.
“Even if I never own the house?”
He nodded.
“Yes. Being obligated on the loan doesn’t automatically give you ownership.”
I turned toward Mom.
“Did you hear that?”
She looked uncomfortable.
“Joel, we weren’t planning on anything going wrong.”
I nodded.
“Neither was I when I started paying six years ago.”
Nick leaned forward.
“You’re making it sound worse than it is.”
I looked toward him.
“Nick, the house is designated for you.”
He shrugged.
“Someday.”
I continued.
“But the loan would be my responsibility immediately.”
For several seconds, he didn’t answer.
Then Mom spoke.
“That’s not a fair way to describe it.”
I looked toward her.
“Then describe it.”
She hesitated.
“You’re family. We all benefit when the house stays in the family.”
I nodded.
“Who benefits from the shop?”
Nick looked away.
I continued.
“Who operates the car business there?”
Nobody answered.
Then I turned toward Mr. Haskins.
“There’s something else I’d like to clarify. When was this loan file opened?”
He checked the screen.
“November tenth.”
I nodded.
“Who told you I would co-sign?”
Mom’s expression tightened.
For a moment, Mr. Haskins seemed uncomfortable.
Then he answered carefully.
“Your mother and brother indicated that you were expected to participate. We still require your direct consent and application.”
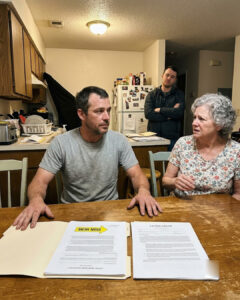
I looked toward Dad.
“Did you know that?”
He frowned.
For several seconds, he stared toward Mom.
Then whispered.
“Darla, you told me Joel offered.”
My mother became still.
Dad turned toward her.
“You said he’d agreed.”
She took a breath.
“Lowell, I said he’d help.”
Dad shook his head slowly.
“No.”
For a moment, I barely recognized his voice.
It was quiet.
But firmer than I’d heard it in years.
“You told me Joel came to you and offered to go on the new loan.”
Mom looked toward Mr. Haskins.
Then toward Nick.
For the first time, she seemed unable to find an answer.
Dad continued.
“You told me it was fair because Nick would inherit the shop and Joel would help keep the payments manageable.”
I stared at him.
For a moment, I felt something tighten in my throat.