I’d seen it there the same night I pulled the refi documents.
Yeah, I know.
I can hear some of you already.
That’s a violation of privacy.
And you’re not wrong.
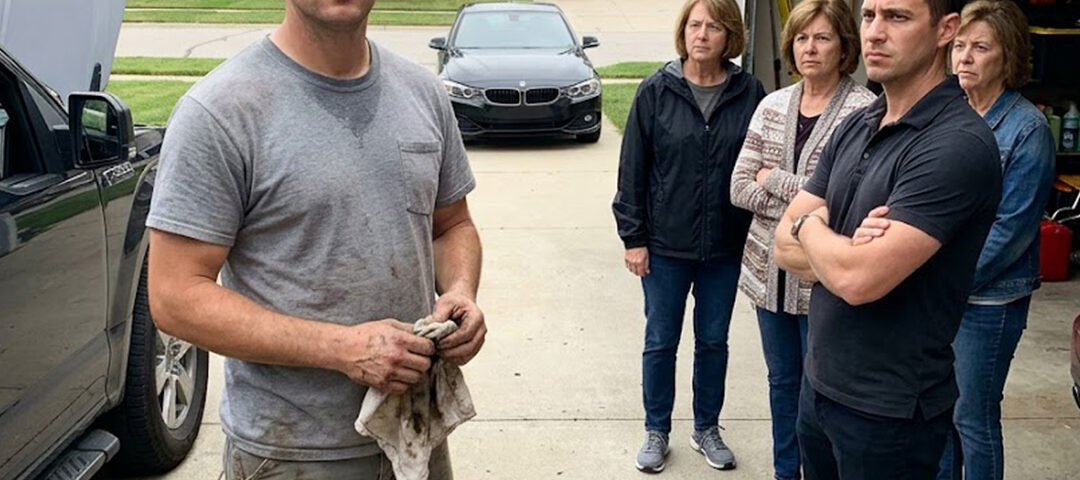
But when your family ambushes you in your driveway and accuses you of hoarding money while your brother drives a leased BMW from your mother’s disappearing equity, you start caring less about etiquette and more about truth.
I logged in on Wednesday night, downloaded 18 months of statements, made a spreadsheet, and then I sat at my kitchen table until 1:00 in the morning because the numbers told a story that was worse than I’d expected.
The second refinance, the one Kyle co-signed, pulled $95,000.
According to the loan documents, those funds were supposed to go toward Kyle’s mobile detailing business.
Equipment, a commercial vehicle, licensing, insurance, marketing.
I found a record of $52,000 going to legitimate business expenses.
A van purchase, equipment, a deposit on a commercial insurance policy.
That left $43,000.
I tracked it through the statements.
About $3,000 went to miscellaneous household expenses for Mom.
The remaining $40,000 had been transferred to an account I didn’t recognize.
Not Mom’s checking.
Not Mom’s savings.
Not the business account for the detailing company.
I searched for the account number across all the statements.
It appeared only twice.
Two transfers, $25,000 and $15,000, both within six weeks of the refi closing.
Then never again.
I didn’t know whose account that was, but I had a strong suspicion.
I called Dale.
“Forty grand to an unknown account,” he said. “And Kyle removed himself from the loan right after?”
“Right before the third refi.”
“He knew the ship was sinking, and he grabbed a life raft on the way out.”
“That’s my read.”
“Your mom know about the forty grand?”
“I don’t think so. She was focused on the detailing business. Kyle handled the money side. She trusted him.”
Dale was quiet for a second.
“Marshall, you need a lawyer.”
“I need to know whose account that is first.”
“You need a lawyer first. Then figure out the account.”
Dale gave me the name of a real estate attorney his sister had used.
Lorie Ashford.
I called her office Thursday morning and had a consultation that afternoon.
I laid everything out.
The three refis, the co-sign, Kyle’s removal, the $40,000 to the mystery account, the current default.
Lorie looked at the documents for about ten minutes without speaking.
Then she took off her reading glasses and said, “Your mother’s house is underwater. Current value is roughly $280,000 based on comparable sales in the area.”
“The outstanding mortgage balance is approximately $310,000.”
She owes more than it’s worth.
“I know.”
“The missing $40,000. If your brother diverted funds from a loan he co-signed, that’s potentially fraud. At minimum, it’s a breach of the loan agreement.”
“Whether your mother has a legal claim against him depends on several factors, but the documentation you have is a strong starting point.”
“I’m not trying to sue my brother,” I said.
“What are you trying to do?”
I thought about it.
Really thought about it.
“I’m trying to stop my family from bleeding my mother dry and then sending me the bill.”
Lorie nodded slowly.
“Then here’s what I’d recommend. Get clarity on that account. If it’s Kyle’s personal account, your mother deserves to know where her money went.”
“Beyond that, the house is likely headed for a short sale or foreclosure regardless. The numbers don’t support any other outcome.”
“Your job right now is to make sure you’re not financially entangled when that happens.”
“I’m not on any of the loans.”
“Good. Keep it that way.”
I spent the next few days acting completely normal.
I answered Mom’s call on Sunday.
Short, pleasant, nothing about money.
She didn’t bring it up either, which told me Kyle and the aunts were probably regrouping for round two.
Meanwhile, I dug into that account number.
I’m not a detective, but I’m a guy who’s good with records, and Kyle isn’t exactly sophisticated.
I searched his social media.
Found an old post from three years ago where he’d bragged about paying off his truck and his credit cards.
Timestamp: six weeks after the second refi closed.
He’d used the $40,000 to clean up his own debts.